Dorchester Multi-Family Investment Analysis: Cash Flow, Zoning, and Value-Add Spreads
Dorchester investor outlook: triple-deckers, 11x–12x GRMs, 4.75%–5.75% caps, ADU potential, Red Line access, and value-tier pockets.
Written BySamuel Al-Harbi
PublishedSeptember 24, 2026
UpdatedNovember 7, 2026
Sam Al-Harbi, REALTOR® · Candor Investment Group powered by eXp Realty · MA Salesperson Lic. #9589109. I own three properties in Massachusetts and help buyers, sellers and investors run the numbers on multifamily and small commercial property across Greater Boston, the Merrimack Valley and Central Mass. Serving Boston, Fitchburg, Worcester, Waltham, Lowell, Norwood, Burlington, Framingham and Newton, MA. License #9589109.
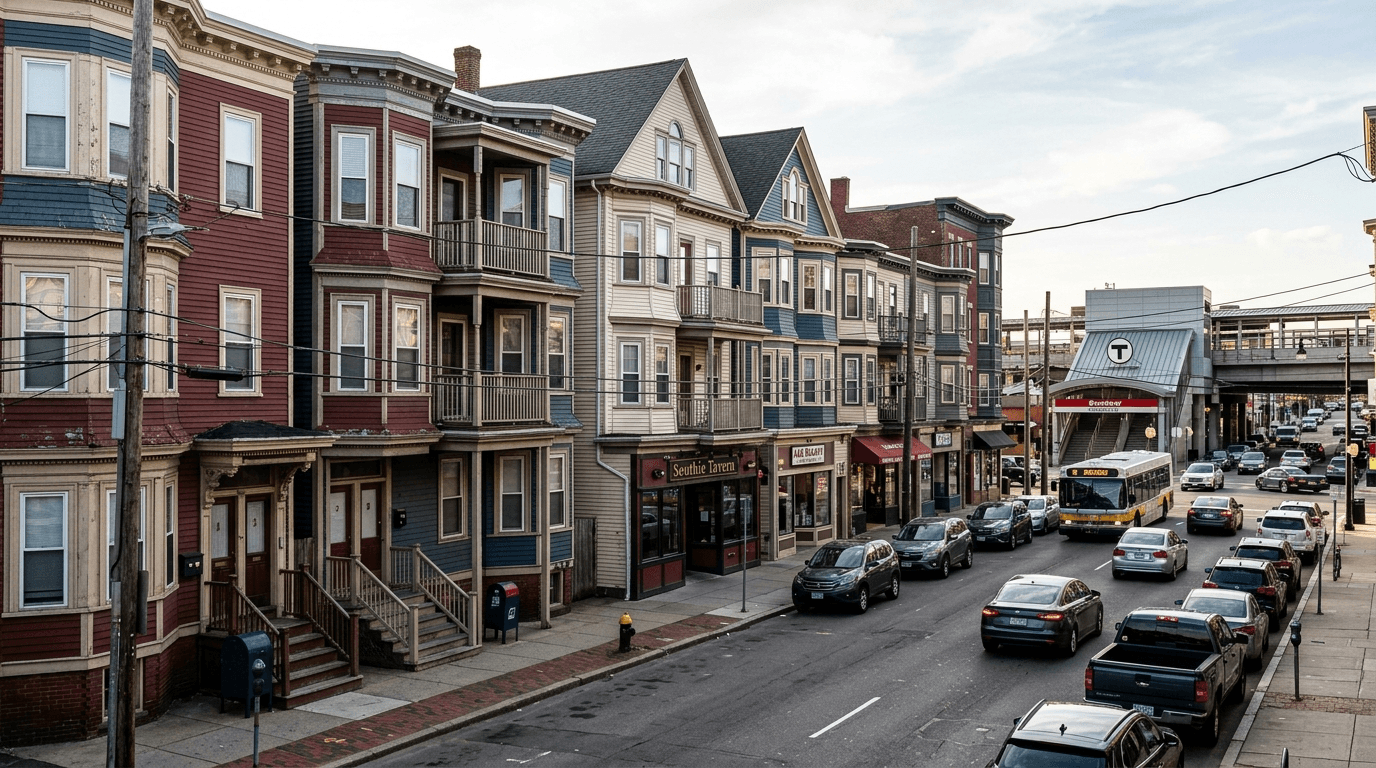
Dorchester moves more triple-deckers than any other neighborhood inside Boston city limits. It's also where the distance between a listing sheet pro forma and a real operating statement is widest. Three questions matter here: what these assets actually yield, where zoning lets you manufacture additional income, and whether the renovation arbitrage survives contact with a contractor's invoice.
What Are Cash Flow Returns Like on Dorchester Multi-Family Properties?
Stabilized two- and three-family properties in Dorchester run at roughly a 4.75% to 5.75% cap rate once you load expenses honestly, with gross rent multipliers in the 11x to 12x range depending on sub-neighborhood and condition. Spreads are compressed. You're not buying yield here. You're buying rent growth, loan paydown, and the option to add value through renovation or an extra unit.
Figures describe housing stock and transactions, not the people who live in an area. Equal Housing Opportunity.
What Does It Cost to Acquire a Multi-Family in Dorchester?
Price bands in 2026 are tight, and the seller pool knows them cold:
Dorchester Multifamily Acquisition Price Bands
Typical 2026 asking-price ranges by multifamily property type highlight the capital stack required for two-family, three-family, renovated, and larger multifamily assets.
Typical 2026 asking-price ranges by multifamily property type highlight the capital stack required for two-family, three-family, renovated, and larger multifamily assets.
•Two-family: $850,000–$1,050,000 → roughly $425,000–$525,000 per unit
•Three-family (unrenovated): $1,000,000–$1,250,000 → roughly $333,000–$417,000 per unit
•Three-family (renovated): $1,250,000–$1,450,000 → roughly $417,000–$483,000 per unit
•Four-family+: $1,300,000+ → varies, but per-unit basis generally improves with door count
Per-unit math is the first calculation I run on any Dorchester deal, and it explains why three-families dominate investor demand. A three-family at $1.15M buys doors at roughly $383,000. A two-family at $950,000 buys them at $475,000: a 24% premium per door even though the neighborhood, the tenants, and the tax rate are the same. The two-family only pencils if the units are materially larger, or if you're an owner-occupant exploiting FHA leverage.
Worth noting: those asking bands sit close to where product actually trades. Sellers are pricing realistically rather than testing the market.
What Rents Do Dorchester Units Actually Command?
Market rent (not pro forma rent) decides whether a deal works:
Look at the gap between unrenovated and renovated three-bedroom rent. That delta (call it $400–$600 per month per unit) is the entire thesis of the value-add section below.
Sub-neighborhood pricing and rent don't move in lockstep. That's where the yield pockets hide:
Neighborhood Pricing vs. Rent: Dorchester Submarkets
A paired view of median listing prices and median monthly rents across selected Dorchester neighborhoods helps identify possible yield-oriented value pockets.
Median listing price
Median monthly rental price
A paired view of median listing prices and median monthly rents across selected Dorchester neighborhoods helps identify possible yield-oriented value pockets.
Read that as a rent-to-price exercise, not a price comparison. Meeting House Hill carries the lowest basis of the three at $520,000, with a median rent of $2,950. Uphams Corner – Jones Hill sits in the middle on price at $606,950 and posts the highest median rent at $3,150. Neponset has the highest basis at $678,900 and the lowest rent at $2,831. Neponset buyers are paying for owner-occupant appeal and Red Line proximity at Ashmont. They aren't being paid in cash flow for it. Neponset buyers are paying for owner-occupant appeal and Red Line proximity at Ashmont. They aren't being paid in cash flow for it.
The pattern repeats across the broader sub-market tiering. Savin Hill, Jones Hill, Ashmont and Lower Mills price at the top. Fields Corner, Uphams Corner, Meeting House Hill, Codman Square and Four Corners price at the value end. Cash flow mandate? Shop the value end. Appreciation and exit liquidity mandate? Pay up for the premium tier and accept a lower going-in yield.
What Cap Rates and GRMs Should You Target on a Dorchester Triple-Decker?
Greater Boston multifamily yield benchmarks by asset class frame the range, and small-asset Dorchester product sits inside these bands:
Greater Boston Multifamily Yield Benchmarks by Asset Class
Cap-rate ranges show how investors are being compensated for moving from stabilized Class A assets into value-add and opportunistic multifamily strategies.
Cap-rate ranges show how investors are being compensated for moving from stabilized Class A assets into value-add and opportunistic multifamily strategies.
Run the GRM as a sanity check before building the full model. A three-family at $1,150,000 collecting three units at $2,700 produces $97,200 gross annual: a GRM of roughly 11.8x. At $1,350,000 renovated, collecting $3,400 per unit, you get $122,400 gross and a GRM of 11.0x. The renovated asset isn't obviously more expensive on a revenue multiple. That's the market telling you renovation capital is priced efficiently.
The expense side is where listing pro formas fall apart. Build your model with:
•Taxes: Boston taxes residential property at a nominal rate per $1,000 of assessed value, and here's the part that matters. Investor-owned property loses the residential exemption. Owner-occupants get a materially lower effective rate. You don't. Use the nominal rate, and confirm the current figure and the parcel's assessed value before you model anything.
•Vacancy: 4%–5% for Dorchester triple-deckers. Turnover is the risk, not chronic vacancy.
•Capex reserve: $300–$500 per unit per year, minimum, on pre-1930 wood-frame stock. Non-negotiable.
•Water/sewer, insurance, heat (if not separately metered): heating configuration is a deal-level question. A single boiler serving all three units shifts a material expense onto the owner and should be discounted accordingly.
Keep rent growth assumptions conservative. Greater Boston rent growth has been roughly flat, and the Class B/C segment these triple-deckers compete in has shown little pricing power. Don't build a model that needs 4% annual rent escalation to clear your hurdle.
Dorchester Investor Snapshot: September 2026
Headline pricing, liquidity, rent, and negotiation indicators for Dorchester as of September 2026—useful for quickly sizing acquisition conditions in a busy urban submarket.
Liquidity conditions matter on both ends of the trade. Sale-to-list is running at 99%, with sold prices landing 1.48% below asking and a median of 58 days on market against 236 active listings. That's a functioning, reasonably balanced market: not a distressed one. Read those numbers together: well-presented, correctly-priced assets clear inside the median, while overpriced deferred-maintenance buildings sit past it and then cut. Your opportunity as a buyer lives almost entirely in that second bucket.
What Zoning and ADU Opportunities Exist for Dorchester Multi-Family Investors?
Boston permits accessory dwelling units, and Dorchester's lot sizes, basement heights, and detached garage inventory make it one of the better neighborhoods in the city for unit-count expansion. The catch: the ADU pathway is meaningfully easier for owner-occupants than for pure investors, and parking and FAR constraints will kill a material share of candidate parcels. Verify at the parcel level before you assign a dollar of value to it.
How Does Boston's ADU Policy Apply to Dorchester Multi-Family Properties?
The core structure:
•Owner-occupancy is the friction point. Boston's ADU framework has historically been oriented toward owner-occupied properties. If you're an investor-owner without occupancy, treat ADU conversion as a variance-dependent path, not an as-of-right one. Confirm current Inspectional Services and Boston Planning Department requirements for your specific parcel before you count on the income.
•Basement conversions are the most common Dorchester project. Triple-deckers here frequently have full-height basements. The binding constraints are ceiling height, egress, light and ventilation, and flood/moisture. Flood risk is higher in the low-lying areas near Neponset and the Bay. It affects whether a basement works at all and what insurance costs. Pull parcel-level flood data before you budget a basement unit.
•Detached garage and carriage house conversions are the second pathway, and Dorchester's older lots carry more of this stock than most Boston neighborhoods.
When it works, the financial case is strong. A conforming basement studio or one-bedroom should rent in the $2,100–$2,350 range based on neighborhood medians. At a $150,000–$200,000 all-in conversion cost, that's $25,000–$28,000 in gross annual rent on $175,000 of capital: a gross yield north of 14% before expenses, plus a value creation event at a 5.25% cap that can exceed the cost basis by a wide margin.
Run that math carefully. The conversions that blow budgets are the ones that hit underpinning for ceiling height, a new egress stairwell, or a sewer line that needs replacing.
What FAR, Parking, and Variance Constraints Limit Unit Expansion in Dorchester?
Work this checklist before you assign ADU value to an acquisition:
1. Existing FAR vs. district maximum. Many Dorchester triple-deckers already sit at or over the current FAR limit for their subdistrict: they predate the zoning. A building that's already non-conforming has limited headroom for lawful expansion of gross floor area, though interior conversion of existing space is a different question than new construction.
2. Off-street parking. The most common ADU killer in the neighborhood. Adding a fourth unit to a three-family on a narrow lot with two spaces triggers a parking deficiency in most subdistricts. Boston has been directionally relaxing parking minimums, especially near transit, but don't assume relief. Verify it.
3. Lot coverage and rear yard setbacks. Detached ADU construction runs into these constantly on Dorchester's deep-but-narrow lots.
4. Zoning Board of Appeal timeline. Budget 6–12 months plus real legal and architectural cost for a variance, and price that carry into your model. A deal that only works after a successful ZBA vote is an option, not a cash flow asset. Model it that way.
Where Are the Best Transit-Oriented Development Opportunities in Dorchester?
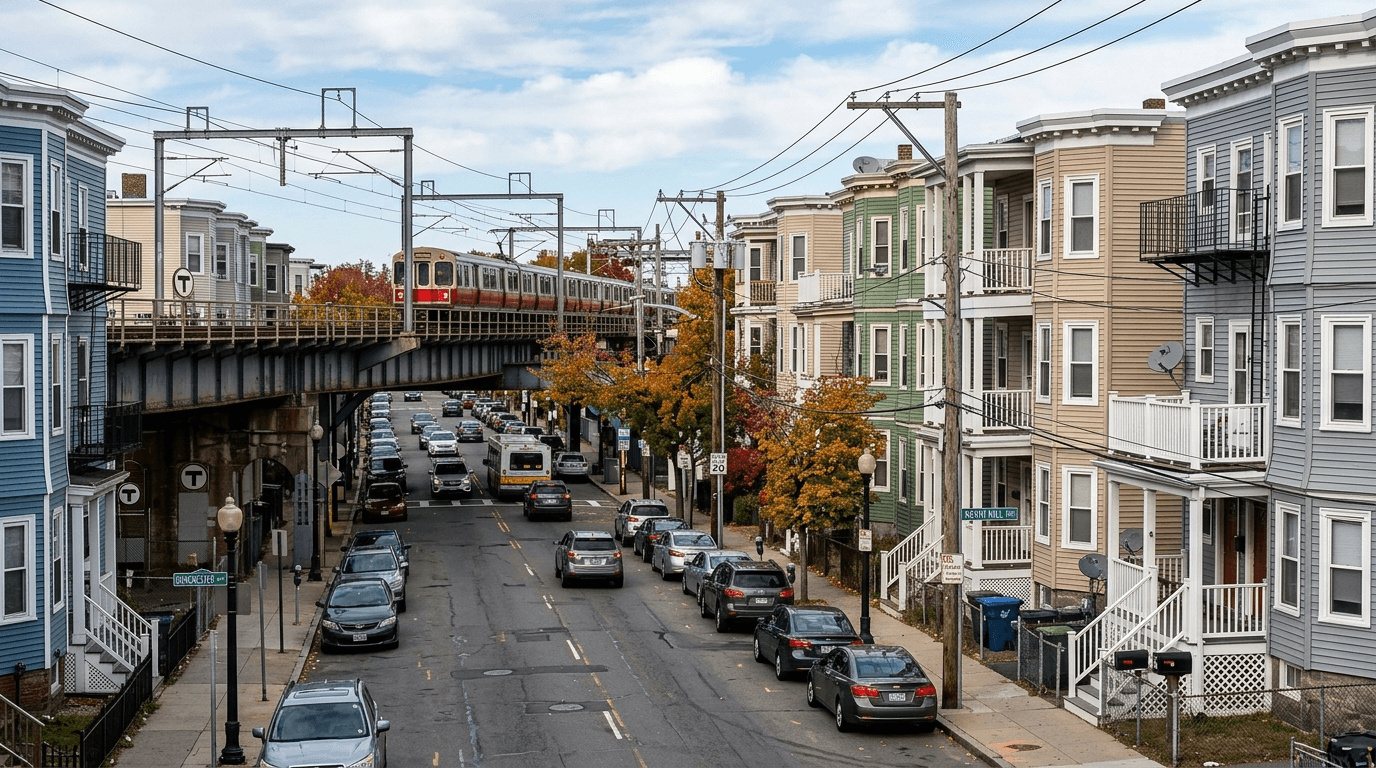
The Red Line spine is the neighborhood's structural advantage: JFK/UMass, Savin Hill, Fields Corner, Shawmut, and Ashmont, plus the Ashmont–Mattapan high-speed trolley and Fairmount Line commuter rail.
Transit proximity does two things for investors. It supports rent premiums and reduced parking expectations, and it marks the parcels where the city is most willing to entertain density. Sites within a quarter mile of a Red Line head give a parking-relief argument its best odds.
The biggest signal in the forward pipeline:
$5,000,000,000Project Value
Dorchester Bay City Waterfront Transformation
Major development activity can reshape tenant demand, neighborhood perception, and long-term asset values. Dorchester Bay City is the standout project-scale signal for investors tracking future growth corridors.
A $5 billion, 36-acre waterfront redevelopment adjacent to the JFK/UMass corridor isn't a cash flow event. It's a basis event. Projects at that scale reshape rents and comparable sales over a 10-15 year horizon. Buying for a long hold? Proximity to that corridor is a defensible reason to accept a lower going-in yield. Buying for a 3-5 year BRRRR exit? It isn't, and you shouldn't pay for it.
Supply context matters too. New deliveries in Boston are overwhelmingly Class A, which competes with triple-decker units at the margin but not head-on. Older Class B/C stock in Dorchester faces effectively zero new competing supply. That's the structural bid under your rent roll.
What Is the 'Fixer-Upper' Spread in Dorchester and Is It Worth the CapEx?
The observable spread between an unrenovated three-family and a renovated one runs roughly $250,000. The $1,000,000–$1,250,000 band against the $1,250,000–$1,450,000 renovated band. A full gut of three units typically costs $250,000–$400,000. Do the subtraction: cosmetic-to-moderate rehab is where the arbitrage lives. A full gut is close to a wash unless you buy materially below the bottom of the unrenovated band.
What Is the Price-Per-Square-Foot Delta Between Distressed and Turnkey Dorchester Multi-Families?
Dorchester's median sale price per square foot runs around $465, against a median sold price of $635,000 and a median listing price of $619,500. Those headline numbers blend condo, single-family and small multifamily product, so use the per-foot figure as a cross-check on condition rather than as a valuation input on a three-family.
Stack the bands:
Data Table
Asset condition
Typical price
Per-unit basis (3-family)
Unrenovated three-family
$1.00M–$1.25M
$333K–$417K
Renovated three-family
$1.25M–$1.45M
$417K–$483K
Observed spread
~$250K
~$83K/unit
The rent side supports it. A renovated 3BR commands $3,000–$3,700 versus $2,600–$3,100 for the same unit in dated condition. Call it $450 per month per unit of achievable lift on a like-for-like basis, or $16,200 annually across three units. Capitalized at 5.25%, that income lift alone is worth roughly $309,000 in value creation. If the floor plan also supports reconfiguring a dated two-bedroom into a three-bedroom, the lift grows, but that's a second, separate bet with its own construction cost. Run those numbers separately rather than folding it into the renovation spread.
So why does the observed market spread sit at only ~$250,000? The market is pricing execution risk, carry cost, and the reality that not every building supports a full three-bedroom reconfiguration. The gap between $309,000 of theoretical value creation and the $250,000 observed spread is your margin. It's thin enough that a $60,000 overrun erases it.
What Are Realistic CapEx Budgets for a Dorchester Triple-Decker?
Working numbers for pre-1930 wood-frame stock. Verify with your own contractor for your specific building:
Per-unit interior work:
•Kitchen, full replacement: $25,000–$45,000
•Bathroom, full replacement: $15,000–$25,000
•Flooring, paint, trim, doors: $15,000–$25,000
•Electrical, full rewire of unit: $15,000–$25,000
Building-wide systems:
•Roof replacement: $25,000–$45,000
•Heating conversion to separate gas systems: $30,000–$50,000
•Full electrical service upgrade and separate metering: $25,000–$40,000
•Windows, full building: $30,000–$60,000
•Exterior siding/trim/porches: $40,000–$100,000 (triple-decker porch systems are a chronic and expensive problem here)
•Knob-and-tube remediation, asbestos, lead paint compliance: $20,000–$60,000+
Realistic totals:
•Cosmetic refresh, three units: $75,000–$125,000
•Moderate rehab (kitchens, baths, mechanicals, no structural): $175,000–$275,000
•Full gut, three units: $250,000–$400,000+
Add 15% contingency, and plan on using it. Two items break budgets more than anything else: porch and structural framing rot discovered behind the siding, and lead paint compliance, because the state's lead law applies to pre-1978 units.
Budget carry as well. At current rates, six to nine months of debt service, taxes, and insurance on a $1.1M acquisition is real money, and Dorchester permitting timelines are not fast.
What Cash-on-Cash Return Should a Dorchester BRRRR Target?
Framework for a three-family value-add:
Acquisition and stabilization:
•Purchase, unrenovated three-family: $1,050,000
•Investor down payment at 25%: $262,500
•Rehab (moderate, funded partly with cash): $200,000
•Closing, carry, contingency: $60,000
•Total cash in: ~$522,500
Post-stabilization:
•Three units at $3,300 renovated market rent: $118,800 gross annual
•Less vacancy at 5%, operating expenses, taxes at the non-exempt nominal rate, and capex reserve: NOI in the $70,000–$78,000 range depending on heat configuration and insurance
•Value at a 5.25% cap on $74,000 NOI: ~$1,410,000
Refinance:
•70% LTV on $1,410,000: $987,000
•Existing debt retired: $787,500
•Cash out: ~$199,500. Roughly 38% of capital recovered
Resulting metrics:
•Cash remaining in deal: ~$323,000
•Cash flow after new debt service: thin to modestly positive. That's the honest answer for Dorchester at current rates.
•Cash-on-cash: 2%–5%
•Value above all-in cost: ~$100,000 over an 18-month execution. That is the ~$1,410,000 stabilized value less ~$1,310,000 of purchase price ($1,050,000), rehab ($200,000) and closing, carry and contingency ($60,000).
•Equity after the refinance: ~$423,000. That is the ~$1,410,000 value less the ~$987,000 new loan, with ~$323,000 of your cash still in the deal.
•Equity multiple on a 5-year hold: 1.7x–2.1x. This is one modeled scenario. It assumes modest rent growth and principal paydown, and it is not a promised or typical result.
That's the realistic picture. Dorchester in 2026 is not a cash-flow-on-day-one market for leveraged investors buying at market. The return sits in forced appreciation and principal paydown. Anyone showing you a Dorchester triple-decker with a 10% cash-on-cash return at 25% down is either using a residential exemption they won't qualify for, ignoring capex reserves, or quoting pro forma rents the building can't currently achieve.
Where Does the Dorchester Deal Actually Get Made?
Three conditions:
1. Buy in the value tier, not the premium tier. Codman Square, Four Corners, Uphams Corner and Meeting House Hill deliver a lower basis against rents that aren't proportionally lower. Meeting House Hill, the cheapest of the three areas compared above at $520,000, is the first place to check.
2. Buy the listings that have already cut. Sold prices land about 1.48% below asking on a median of 58 days, and the buildings that sit longer than that are the ones that eventually reduce. Those are your negotiation targets. Properties clearing at or above asking are going to owner-occupants using FHA at 3.5% down, and you can't win that bid on an investor loan without destroying your returns.
3. Buy where there's a second lever. A dated three-family with a full-height dry basement and adequate lot area is worth more than one without, because you're buying the renovation spread and the unit-count option together. Price the option conservatively, but recognize it exists.
The seller pool here is sophisticated and the price bands are well-publicized. You won't find mispriced assets by browsing. You find them by running the numbers on the ones everyone else walked away from, and knowing exactly why they walked.
Figures above are drawn from published market data as of September 2026 and should be verified against current MLS data, the specific property's actual rent roll and operating history, and parcel-level zoning research before any offer is submitted.
Tools, not advice: this guide walks through the process many Massachusetts investors use to run their own numbers on a property, using many of the same tools and steps successful Massachusetts investors rely on. Every cap rate, yield, ROI and value-creation figure above is an illustrative estimate built on the stated assumptions and the dated third-party sources cited in this article. It is not an appraisal, a guarantee of rent, income, appreciation or return, and not investment, financial, tax, or legal advice. Zoning, tax and legal information in this guide is general and current as of September 2026. Confirm specifics with the local Building or Inspectional Services Department and consult your own CPA and attorney before relying on it. Run your own numbers on the Investment Calculator and verify every figure independently.
Are Dorchester multi-family properties in Boston, MA good cash-flow investments?
Dorchester two- and three-family properties currently run at about a 4.75% to 5.75% cap rate on realistic expenses, with gross rent multipliers generally in the 11x to 12x range. For leveraged investors buying at market, Dorchester rewards rent growth, loan paydown, and renovation more than it rewards day-one cash flow.
What does it cost to buy a two-family or three-family in Dorchester, Boston, MA?
Two-family properties in Dorchester typically price around $850,000–$1,050,000, or roughly $425,000–$525,000 per unit. Three-family properties usually price around $1,000,000–$1,250,000 unrenovated and $1,250,000–$1,450,000 renovated, making the three-family format more efficient on a per-door basis.
What rents can multi-bedroom apartments command in Dorchester, Boston, MA?
Two-bedroom units in Dorchester two-family properties typically rent for about $2,600 to $3,100, while two-bedroom units in three-families typically rent for about $2,400 to $3,000. Three-bedroom units in unrenovated three-families rent around $2,600 to $3,100, while renovated three-bedroom units can reach about $3,000 to $3,700.
How is the commute and public transportation access in Dorchester, Boston, MA?
Dorchester has strong transit access through the Red Line spine, including JFK/UMass, Savin Hill, Fields Corner, Shawmut, and Ashmont. The neighborhood also has access to the Ashmont–Mattapan high-speed trolley and Fairmount Line commuter rail service.
Which parts of Dorchester, Boston, MA are more affordable for investors?
Fields Corner, Uphams Corner, Meeting House Hill, Codman Square, and Four Corners are the value-end submarkets in Dorchester. Savin Hill, Jones Hill, Ashmont, and Lower Mills price at the higher end, where investors generally accept lower going-in yields in exchange for appreciation potential and exit liquidity.
Are condos or townhomes the main investor opportunity in Dorchester, Boston, MA?
Dorchester’s highest-volume investor market is the triple-decker, not condos or townhomes. The neighborhood’s median price-per-square-foot figure reflects a mix of condos, single-family homes, and small multifamily properties, so investors typically use it as a condition cross-check rather than the main valuation tool for three-family assets.
Can ADUs improve the value of Dorchester properties in Boston, MA?
Boston permits accessory dwelling units, and Dorchester has many properties with full-height basements, detached garages, and older lots that may support unit-count expansion. The path is easier for owner-occupants than pure investors, and parking, FAR, ceiling height, egress, ventilation, and flood or moisture issues can limit feasibility.
What renovation costs matter most for older Dorchester multi-family homes in Boston, MA?
Dorchester triple-deckers are often pre-1930 wood-frame buildings, so investors should budget for recurring capex and building-wide systems. Common cost drivers include roofs, heating separation, electrical upgrades, windows, siding, porches, knob-and-tube remediation, asbestos, and lead paint compliance, since the state's lead law applies to pre-1978 units.
Why work with Sam Al-Harbi in Dorchester, Boston?
Sam Al-Harbi, REALTOR® · Candor Investment Group powered by eXp Realty · MA Salesperson Lic. #9589109. Call (978) 267-7409 or send a message through the contact page.