South Boston Multi-Family Investment Outlook: ROI, Zoning, and Value-Add Spreads
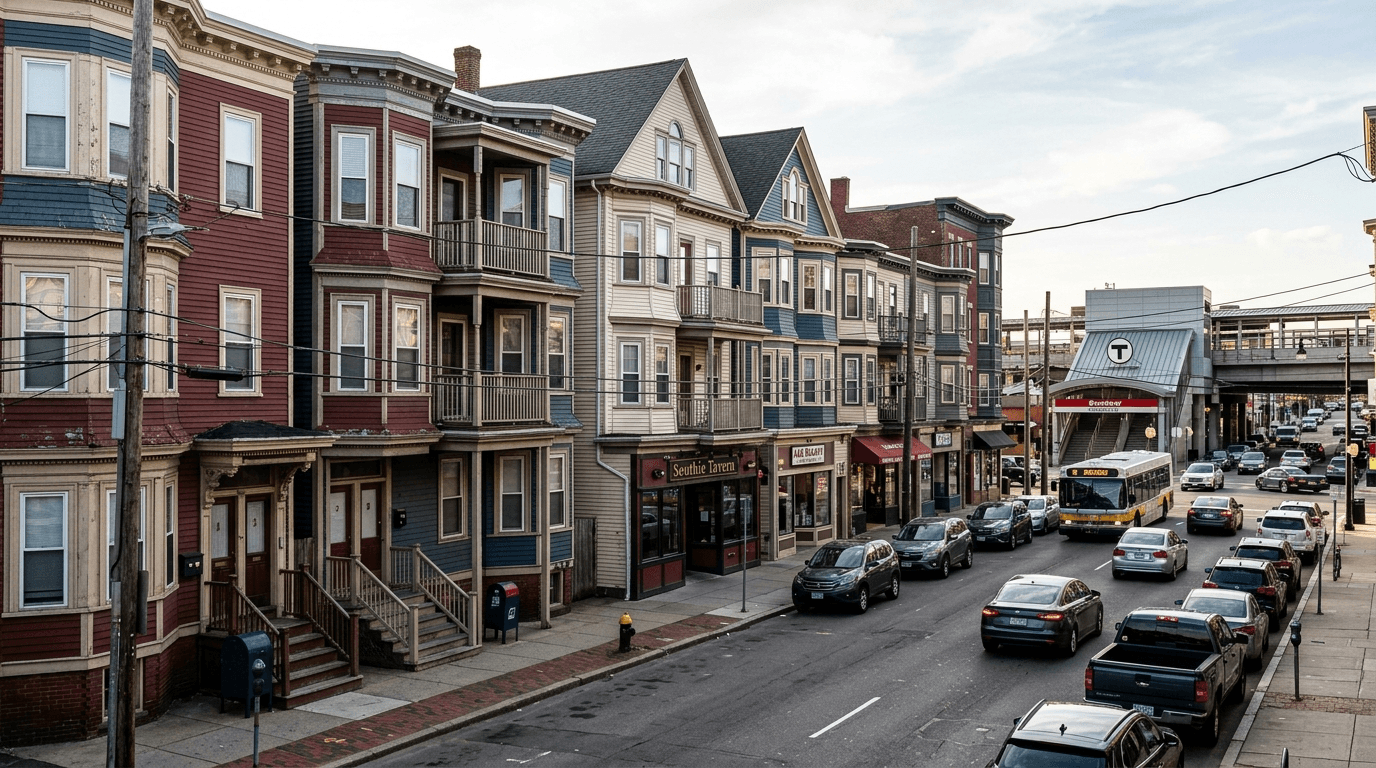
South Boston’s transit-rich, low-vacancy vibe: 4.8% gross yields, 1.26% vacancy, $3,817 average rent, ADU upside near Broadway/Andrew.
Written BySamuel Al-Harbi
PublishedSeptember 24, 2026
UpdatedNovember 7, 2026
Sam Al-Harbi, REALTOR® · Candor Investment Group powered by eXp Realty · MA Salesperson Lic. #9589109. I own three properties in Massachusetts and help buyers, sellers and investors run the numbers on multifamily and small commercial property across Greater Boston, the Merrimack Valley and Central Mass. Serving Boston, Fitchburg, Worcester, Waltham, Lowell, Norwood, Burlington, Framingham and Newton, MA. License #9589109.
Yields are compressed here. Liquidity is not. South Boston posts some of the highest rents in the city, vacancy that rounds to nothing, and acquisition pricing that reflects both facts in full. You don't find deals in this submarket: you build them, through unit reconfiguration, zoning capture, or a disciplined renovation spread. Here's how the September 2026 numbers work.
What Cash Flow Can You Actually Expect From a South Boston Multi-Family?
On an all-cash basis, expect gross rental yields near 4.8%. After taxes, insurance, maintenance and reserves, the net cap rate lands below that figure. South Boston is not a day-one cash flow market: it is an appreciation and rent-growth market where cash flow arrives in years three through five.
Start with the top line. As of August 2026, the South Boston median sale price sits at $917,057, up 4.0% year over year, with median days on market at 28. Multi-family product trades wider than that median. Two-to-four unit and small mixed-use buildings span a broad range depending on unit count, condition, and how close you are to the Seaport, with larger assemblages pricing well above the single-family and condo median.
Figures describe housing stock and transactions, not the people who live in an area. Equal Housing Opportunity.
South Boston Investor Snapshot: Pricing, Rent & Liquidity
Headline metrics for an investor outlook: South Boston shows high pricing, strong rents, low vacancy, and relatively quick rental turnover despite rising availability.
What Does Acquisition Cost Per Unit Look Like in South Boston?
Back into it from the neighborhood median. At $917,057, a two- or three-unit building in South Boston prices materially above that figure in most cases, and per-door basis lands well above what the broader Boston multi-family market averages. The premium is real, and it widens as you move toward the Seaport and the Broadway corridor.
That premium is the first thing I stress-test with clients. You're paying up for a location with 1.26% vacancy and an 8-day median rental days on market. The question is whether the rent premium compensates for the price premium. Usually it partially does. Rarely does it fully.
What Are Current Market Rents by Unit Type in South Boston?
South Boston Average Rent by Bedroom Count
Larger unit counts command materially higher monthly rents, highlighting the revenue premium for family-sized or roommate-oriented layouts in dense South Boston.
Larger unit counts command materially higher monthly rents, highlighting the revenue premium for family-sized or roommate-oriented layouts in dense South Boston.
Average monthly rent across all South Boston product is $3,817. By bedroom count:
•Studio: $2,515
•1BR: $3,029
•2BR: $3,589
•3BR: $4,520
•4BR: $5,619
•5BR: $7,049
Look at the slope. The jump from 2BR to 3BR is $931/month. From 3BR to 4BR, another $1,099/month. Per-bedroom revenue efficiency improves materially as unit size grows, and that's the single most important operational insight in this neighborhood. A 4BR unit at $5,619 generates $1,405 per bedroom. A 1BR at $3,029 generates $3,029 per bedroom, but you can't fit four 1BRs into the footprint of one 4BR triple-decker floor without a full gut and a permit fight.
How Do the Yields Actually Pencil in South Boston?
Build the rent stack from the bedroom data. A three-family delivered as a 3BR, a 3BR, and a 2BR scheduled at market rents produces:
That's the ceiling, not the expectation. It assumes every unit is delivered at full market rent, which almost never happens on acquisition.
The market-wide benchmark is more sober.
Investor Yield Benchmarks: South Boston vs South End
South Boston offers a higher gross rental yield than the South End while both neighborhoods remain heavily renter-oriented—key context for acquisition targeting.
South Boston
South End
South Boston offers a higher gross rental yield than the South End while both neighborhoods remain heavily renter-oriented—key context for acquisition targeting.
South Boston's 4.8% gross rental yield beats the South End's 3.6%, and that 120 basis point gap compounds into real money over a hold period. Both neighborhoods are majority renter-occupied, 60% in South Boston versus 69% in the South End, so tenant demand isn't what separates them. Price basis is.
What Kills NOI in South Boston?
Three line items destroy South Boston pro formas more often than anything else.
1. Property taxes. Boston's residential rate is favorable relative to surrounding towns, but assessed values here have been chasing sale prices. Massachusetts assessors value every property each year as of January 1. Boston compares most residential properties with similar properties sold in the past year, so your price can show up in later assessments. Never use the seller's current tax bill in your numbers. Basing the tax bill on your purchase price is the cautious way to run it.
2. Insurance. This is the one most investors miss. A meaningful share of South Boston sits in coastal flood-exposed territory with high wind exposure, and a standard DP-3 form on a 2-4 unit triple-decker in a coastal flood zone is not priced like a DP-3 in Norwood. Get a bound quote before you clear diligence, not after.
3. Capex reserves on 100-year-old stock. Most of the 2-4 unit inventory here predates 1930. Budget a real reserve: not the $250/unit/year line item you see on broker pro formas.
Apply those honestly and the headline gross yield comes down to a lower net cap rate. Run it on the actual rent roll and tax bill.
Boston Multifamily Price Index Forecast
Forecasted Boston 3-star multifamily pricing momentum continues upward from 2028 through 2030, a useful signal for investors underwriting exit values.
Forecasted Boston 3-star multifamily pricing momentum continues upward from 2028 through 2030, a useful signal for investors underwriting exit values.
The Boston 3-star price index is forecast at 279 in 2028, 286 in 2029, and 294 in 2030. If you're modeling a five-year exit, that forecast supports a modest appreciation assumption. It does not bail out a deal that fails on day-one economics plus a defined value-add plan.
What Are the Zoning and Development Opportunities in South Boston?
South Boston gives you three ways to add value. You can convert underused basement or attic space to an ADU in 2F and 3F zones, add units where Boston's own zoning allows it, or stay below the Article 80 review thresholds that add months to your timeline.
How Does Boston's Article 80 Review Process Affect Small South Boston Investors?
For most 2-4 unit investors, the answer is: it shouldn't, if you structure correctly.
South Boston's development potential sits in three places: ADU conversion of underused basement and attic space under Boston's own citywide ADU zoning, unit-count additions where the lot and zoning allow them, and staying deliberately below the Article 80 review thresholds that add months to your timeline.
Buying a triple-decker and adding a fourth unit puts you nowhere near these thresholds. You're dealing with Inspectional Services and, if you need relief, the ZBA. Residential plan review is measured in business days. A ZBA hearing in weeks. Historic review, where applicable, in weeks to a month or two. Small Project Review with the Boston Planning Department runs months; Large Project Review, many months to more than a year.
The financial takeaway is simple: every month of entitlement delay is a month of carry on acquisition debt with zero offsetting revenue. On a seven-figure purchase at current rates, that's real erosion. Structure your deal to stay in the plan-review lane, not the Large Project Review lane. Boston ISD sits at 1010 Massachusetts Avenue; the review desk is at (617) 635-5300 and worth a pre-offer call on any unit-count project.
Are ADUs Actually Feasible on South Boston Multi-Family Lots?
Feasible, yes. Easy, no.
Permit costs are relatively contained, with no impact fees and no school fees. Compared to most high-cost metros, that's a genuinely investor-friendly fee structure.
The constraint here is physical, not regulatory. Lot coverage is dense: rowhouse and near-rowhouse configurations with 0-foot side setbacks (party wall) and shallow rear yards. There's rarely room for a detached ADU. The realistic option is an attached/internal ADU: finishing a basement or attic level into a legal studio or 1BR.
Feasible, yes. Easy, no. The state's by-right ADU rule does not apply in Boston, because Boston's zoning comes from its own state law. Boston's own rule allows an owner-occupant of a one-, two- or three-family home to add one internal ADU as-of-right, using only the existing building footprint, with no added square footage and no exterior alterations. Except in parts of Mattapan, Boston's zoning does not allow an attached or detached ADU without special zoning approval, and the owner may need a variance from the Zoning Board of Appeal. Condominiums and LLCs are not eligible. The state's half-mile transit parking waiver does not apply in Boston either, so check the parcel's zoning for parking. Permit costs are relatively contained, with no impact fees and no school fees. Compared to most high-cost metros, that is a genuinely investor-friendly fee structure. The constraint is the lot, not the fee schedule.
•Construction cost for a basement conversion: the hard cost is where your deal lives or dies, and Boston metro pricing is not forgiving
•Incremental revenue at market: $2,515/month for a studio, $3,029/month for a 1BR
•At $3,029/month, a completed 1BR ADU generates $36,348/year in gross rent
At a 5% cap, that added income stream carries roughly $727,000 of value creation on a stabilized basis: before the cost to build it. Even at aggressive Boston construction pricing, a legal ADU conversion is frequently the single highest-ROI capital deployment available on a South Boston multi-family. The gating items are ceiling height, egress, and fire separation. Get a contractor and an architect into the basement before you write the offer.
What FAR and Height Limits Apply in South Boston Sub-Districts?
The dimensional envelope is the binding constraint on unit-count projects. Boston residential subdistrict standards:
Data Table
Subdistrict
Max FAR
Front Setback
Side Setback
Rear Setback
1F-5000 (Single-Family)
0.5
15-20 ft
5 ft
20 ft
2F-5000 (Two-Family)
0.8
15 ft
5 ft
20 ft
3F-5000 (Three-Family)
1.0
15 ft
5 ft
20 ft
MFR (Multi-Family)
1.0–2.0
15 ft
10 ft
20 ft
Rowhouse/Townhouse
n/a
n/a
0 ft (party wall)
15-20 ft
Typical height limits across much of the residential fabric run 2 to 3 stories. Minimum lot sizes range 5,000 to 20,000 sq ft depending on district, and a large share of South Boston's historic lots are non-conforming against those minimums. That's why so many projects here route through the ZBA for dimensional relief instead of proceeding by-right.
Practical read: buy in a 3F zone at FAR 1.0 on a lot already built to 0.95 and you have no envelope left. Your value-add is interior reconfiguration and unit quality, not square footage. Pull the assessor's card and the existing FAR before you count on any expansion.
How Do Parking Minimums Affect South Boston Development Economics?
Parking is the quiet margin killer. Structured or dedicated parking is expensive to build on lots already at or near coverage limits, and surface parking eats yard area that could otherwise support an ADU or satisfy usable open space requirements (50% minimum usable open space in 1F-5000, with comparable standards elsewhere).
The offset is transit. The Red Line at Broadway and Andrew, plus the Silver Line into the Seaport, give you transit options. The MBTA's approved capital plan reinforces that.
$10.3BTotal Capital Plan Budget
MBTA Capital Plan FY2027-2031
Major transit capital investment supports Boston’s long-term urban growth thesis, with billions allocated to system upgrades across the next planning cycle.
A $10.3 billion capital plan covering 660 system upgrades across FY2027-2031 is a long-horizon tailwind for transit-adjacent basis. On a five-to-ten-year hold, transit-oriented parcels near the Broadway and Andrew corridors carry a structurally better exit story than parcels buried deep in the interior grid. Where local process allows parking reductions for transit proximity, take them. Every parking space you don't build is capital redeployed into revenue-generating square footage.
What Is the 'Fixer-Upper' Spread on South Boston Triple-Deckers?
The delta between unrenovated and turn-key South Boston multi-family is narrower than most investors assume, and Boston-metro renovation pricing eats much of it. The profit is not in the finish: it's in the unit-count change, the rent reset, and buying below the comp set.
What Is the Price-Per-Square-Foot Delta in South Boston?
Renovated and near-renovated product sets the top of the comp set, and unrenovated multi-family generally transacts meaningfully below it. The exact discount depends on condition, but tired, owner-occupied, original-condition triple-deckers cluster well underneath the renovated median.
That's the arbitrage. The problem is that the market knows it. Southie is competitive, and distressed multi-family does not sit quietly here. Where you do find an entry point is the listing that has run past the 28-day median and taken a cut.
What Do South Boston Renovations Actually Cost, and What Do They Return?
Boston metro construction pricing is among the highest in the country, and that cost structure flows straight through to labor and materials.
The honest framework: a cosmetic refresh (kitchens, baths, floors, paint, fixtures) will not return its cost in rent alone at current spreads. Market rent for a renovated 2BR is $3,589. A dated but functional 2BR in the same building might rent at a 10-15% discount. So you're chasing roughly $400/month of incremental rent on a project that costs tens of thousands per unit. At a 5% cap, $400/month adds about $96,000 of value. That can work, but only if your renovation budget stays disciplined.
Change the unit count or bedroom count and the math changes completely:
•Converting an unfinished basement into a legal 1BR: +$3,029/month = +$36,348/year
•Reconfiguring a 2BR floor into a 3BR: +$931/month = +$11,172/year
•Reconfiguring a 3BR floor into a 4BR: +$1,099/month = +$13,188/year
Those are the moves that justify Boston construction pricing. Cosmetic renovation is table stakes. Unit and bedroom-count engineering is where the ROI lives.
Does the BRRRR strategy work in South Boston?
Partially. Here's the constraint.
BRRRR requires your all-in basis (purchase plus renovation) to land far enough below stabilized value that a 70-75% LTV refinance returns most or all of your capital. In South Boston, with renovated product priced at the top of the comp set and construction costs elevated, that gap is tight. You need to buy at a genuine discount. Not 5%. Genuine.
Where it works:
•Properties with unfinished basement or attic square footage you can bring into the rentable envelope
•Buildings with long-tenured under-market tenants where a legal turnover produces a step-function rent reset
•Estate sales and deferred-maintenance properties that never hit broad market exposure
Where it doesn't:
•Anything already listed at renovated-comp pricing with "needs updating" in the remarks
•Properties where the envelope is maxed against FAR and there's no room to add units
One thing in your favor: rental liquidity. At 8 days median rental DOM and 1.26% vacancy, lease-up risk after renovation is close to nil. You won't carry an empty stabilized unit for months here the way you might in a softer submarket. That materially reduces the risk premium you need to build into the model.
What structural risks should you price into a South Boston triple-decker?
These buildings are 90 to 120 years old. Diligence items that regularly generate five-figure surprises:
•Knob-and-tube wiring. Common in original-condition stock. Insurers increasingly won't bind a policy over it. A full rewire on a three-family is a major line item and often non-negotiable before you can place coverage.
•Structural settling and sill rot. Wood-frame construction on filled land: much of South Boston sits on historic fill. Check the basement sills, look for out-of-plumb door frames, get a structural engineer if anything reads off.
•Coastal flood exposure. A meaningful share of the neighborhood carries elevated coastal flood risk. Climate Ready Boston's CFROD standard plans against future sea level rise and a 1% annual-chance flood zone. If your building is in the zone, price flood insurance, price potential future resilience retrofits, and understand that your exit buyer will price it too.
•Asbestos and lead. Standard for the vintage. Abatement is a scheduled cost, not a surprise: budget it in the model rather than discovering it at week three.
•Egress and fire separation. The single most common reason basement ADU conversions die. Confirm ceiling height and a code-compliant egress path before you commit capital.
What Should Investors Take Away From the South Boston Numbers?
The numbers, stripped of narrative:
•Acquisition basis: median sale price $917,057, up 4.0% year over year, with multi-family per-door pricing above the Boston average
•Revenue: average rent $3,817, with a steep premium for larger units
•Risk profile:1.26% vacancy, 8-day rental DOM, 28-day sale DOM: exceptional liquidity on both sides
•Yield: gross rental yield near 4.8%, ahead of the South End's 3.6%, with a net cap rate below that once expenses come out
•Value-add potential: ADU and bedroom-count conversion in 2F/3F zones with no impact fees, plus a Boston multi-family price index forecast to reach 294 by 2030
South Boston is a low-vacancy, high-basis, appreciation-weighted market. It isn't where you go for an 8% day-one cash-on-cash return. It's where you go for near-zero lease-up risk, steady rent growth, and a value-add path through zoning and unit configuration rather than granite countertops.
Bring me a deal here and the first three things I'll ask for are the current rent roll with lease expirations, the assessor's card with existing square footage and FAR, and a bound insurance quote. Those three documents will tell you whether the deal works before you spend a dollar on inspection.
Tools, not advice: this guide walks through the process many Massachusetts investors use to run their own numbers on a property, using many of the same tools and steps successful Massachusetts investors rely on. Every cap rate, yield, ROI and value-creation figure above is an illustrative estimate built on the stated assumptions and the dated third-party sources cited in this article. It is not an appraisal, a guarantee of rent, income, appreciation or return, and not investment, financial, tax, or legal advice. Zoning, tax and legal information in this guide is general and current as of September 2026. Confirm specifics with the local Building or Inspectional Services Department and consult your own CPA and attorney before relying on it. Run your own numbers on the Investment Calculator and verify every figure independently.
Is South Boston in Boston, MA a strong market for multi-family investment?
South Boston is a high-rent, low-vacancy submarket with strong liquidity. Vacancy is 1.26%, median rental days on market are 8, and median sale days on market are 28, which points to very low lease-up risk and active buyer demand.
What cash flow can investors expect in South Boston, Boston, MA?
South Boston is not a strong day-one cash-flow market. Gross rental yields are near 4.8%, and the net cap rate after taxes, insurance, maintenance and reserves is lower.
How expensive are homes and multi-family properties in South Boston, Boston, MA?
The South Boston median sale price is $917,057, up 4.0% year over year. Two- to four-unit properties generally price above that median, with per-door pricing at a premium to the broader Boston multi-family average, especially near the Seaport and Broadway corridor.
What are average rents in South Boston, Boston, MA?
Average monthly rent in South Boston is $3,817. By unit type, studios average $2,515, 1-bedrooms average $3,029, 2-bedrooms average $3,589, 3-bedrooms average $4,520, 4-bedrooms average $5,619, and 5-bedrooms average $7,049.
How is the commute and transportation access in South Boston, Boston, MA?
South Boston has transit access through the Red Line at Broadway and Andrew, plus Silver Line access into the Seaport. This gives you transit options, especially for properties near the Broadway and Andrew corridors.
Are condos, townhomes, and rowhouse-style properties common investment considerations in South Boston, Boston, MA?
South Boston has dense rowhouse and near-rowhouse configurations, often with 0-foot side setbacks and shallow rear yards. These conditions can limit exterior expansion, making interior reconfiguration, basement or attic conversion, and unit-quality improvements more realistic value-add strategies than detached additions.
Can investors add ADUs to South Boston properties in Boston, MA?
ADUs can be feasible in South Boston, especially as attached or internal conversions in basements or attics. Multifamily properties in 2F and 3F zones can add units under the current framework, and ADU projects have no impact fees or school fees.
What costs most affect affordability for South Boston real estate investors?
The biggest cost risks are property taxes that follow rising assessed values, coastal flood or wind-related insurance premiums, and capital reserves for older housing stock. Much of the 2- to 4-unit inventory predates 1930, so investors should budget for structural, electrical, lead, asbestos, egress, and fire-separation issues.
Why work with Sam Al-Harbi in South Boston, Boston?
Sam Al-Harbi, REALTOR® · Candor Investment Group powered by eXp Realty · MA Salesperson Lic. #9589109. Call (978) 267-7409 or send a message through the contact page.