Framingham, MA Multi-Family Investor Outlook: Cash Flow, ADUs & BRRRR Strategy
Downtown Framingham’s dense commuter-rail vibe: 9 multifamily listings, $2,354 rents, $40M reinvestment, and ADU upside for investors.
Written BySamuel Al-Harbi
PublishedSeptember 24, 2026
I'm Sam Al-Harbi, a Boston investor-Realtor who owns 3 buildings and 8 doors. I help buyers, sellers and investors build multifamily and commercial portfolios across Greater Boston. Serving Boston, Worcester, Waltham, Lowell, Norwood, Burlington, Framingham, Fitchburg and Newton, MA. License #9589109.
Framingham, MA
Region
# Framingham, MA Multi-Family Investment Analysis
Framingham is one of the few MetroWest markets where you can underwrite a 2-4 unit deal without inventing rent growth to make it pencil. It's also one of the tightest small multi-family markets in the region by listing count. Translation: your acquisition problem is sourcing, not analysis. What follows is the September 2026 read on cash flow, zoning-driven yield expansion, and the value-add spread.
What Do Multi-Family Cash Flow Numbers Look Like in Framingham, MA?
Direct answer: Framingham multi-family currently trades at a yield that works for leveraged buyers only with disciplined expense assumptions and, in most cases, a value-add or unit-addition component. Cap rates on stabilized 2-4 unit product in this submarket are compressed by residential-comp pricing, not income.
Start with supply, because it governs everything downstream. Per MLSPIN data as of May 2026, Framingham showed just 9 active multi-family listings and 2 closed sales for the period. That is not a market with a functioning price discovery mechanism. With sample sizes that thin, there is no credible "multi-family median" to underwrite against. You underwrite off the residential comp set and the rent roll. Full stop.
For the residential comp set, MLSPIN reports the following as of July 2026:
•Single family median sale price: $755,000, median DOM 18 days, 3.3 months of supply, 128 active listings on 35 closed sales.
•Condo/townhouse median sale price: $350,450, median DOM 37 days, 8.8 months of supply, 91 active listings on 8 closed sales.
•All property types combined: median sale price $695,000, median DOM 21 days, 5.1 months of supply, 255 active listings on 43 closed sales.
That single-family/condo split is the most important underwriting input on this page. A 2-4 unit in Framingham gets priced by appraisers and sellers against the $755,000 single-family bar, plus a rent-roll premium. But the exit for individual units, if you ever condo-convert, prices against a $350,450 condo median. Know which side of that gap your business plan sits on before you write an offer.
Headline July/August 2026 indicators show a competitive market with above-list closings, modest annual value growth, and meaningful available inventory for investors tracking entry points.
Zillow's ZORI puts average Framingham rent at $2,354 as of August 31, 2026, against a national average of $1,948. The direction matters more than the level: that index is -0.7% month-over-month and -2.6% year-over-year. Rents are flat to softening. Do not model 3% annual rent growth into year one of a Framingham pro forma right now. Model zero. Let upside be a surprise rather than a requirement.
Practical rent assumptions I use when modeling a Framingham three-decker or two-family:
•2BR units: the local 2BR benchmark has been quoted around $2,100/mo in older survey data; current market-rate turnkey 2BRs in decent condition underwrite closer to the citywide ZORI average of $2,354. Split the difference at $2,150–$2,300 for a renovated unit, less for tired stock.
•3BR units: carry a premium over the citywide average, but the tenant pool is more income-constrained. Underwrite conservatively.
•Vacancy: 5% minimum. The rental demand is real — 38.7% of Middlesex County homes are renter-occupied, and 50% of Framingham renters are cost-burdened. Units lease. They also sit at the top of the affordability band, which caps how hard you can push above market.
What Do Operating Expenses Actually Run in Framingham, MA?
Framingham's FY2025 residential tax rate is $11.94 per $1,000 of assessed value — 4% below the Massachusetts statewide average of $12.40. On a $750,000 assessment that's roughly $8,955/year. A genuine advantage versus several comparable inner-ring markets, and worth 20-30 basis points of cap rate on its own.
Everything else is where Framingham underwriting goes sideways:
•Water/sewer: most older 2-4 units here are single-metered. Budget it as an owner expense unless you verify RUBS or sub-metering.
•Heat: if the seller's pro forma shows tenant-paid heat, verify at the boiler, not on the listing sheet. Multi-zone conversions on a triple-decker cost real money.
•Snow:47 inches of annual snowfall versus a 28-inch national average. That's a line item, not a rounding error.
•CapEx reserve: $300–$400/unit/year minimum on pre-1940 stock, and Framingham's small multi-family inventory skews old.
The honest math: at a $750,000 acquisition on a three-family grossing roughly $6,600/mo ($79,200/yr), with 5% vacancy, taxes near $9,000, and a 38-42% operating expense ratio, NOI lands in the $44,000–$47,000 range. Call it a 5.9%–6.3% unlevered cap. With current financing, that's thin-to-neutral cash flow on a 25% down conventional structure and negative on anything more leveraged. Framingham is not a day-one cash flow market at retail pricing. It's an appreciation-plus-forced-equity market with tax-rate support. Buy accordingly.
Home Value Benchmark: Framingham vs County, State, and U.S.
Framingham’s typical home value is nearly in line with the Massachusetts benchmark, below Middlesex County, and well above the U.S. national median—useful context for relative value positioning.
Framingham’s typical home value is nearly in line with the Massachusetts benchmark, below Middlesex County, and well above the U.S. national median—useful context for relative value positioning.
Framingham's typical home value of $663,061 sits essentially on top of the Massachusetts benchmark of $661,896, below Middlesex County's $814,047, and well above the national median of $368,697. You are buying Middlesex County location and school access at a statewide price basis. That relative discount is the entire thesis.
What Are the Zoning and ADU Development Opportunities in Framingham, MA?
Direct answer: Framingham's ADU pathway and its severe structural undersupply of multi-family units make unit-addition the highest-ROI lever available to a small investor here — but the math only works on internal conversions, not new detached construction, at current rent levels.
The supply gap should shape every development decision in this city:
Annual Housing Production Gap: Permits vs Projected Demand
Projected annual need materially exceeds historical permitting levels, especially for multi-family units—an investor-relevant signal for supply-constrained rental and infill strategies.
Permitting (2000-2012)
Projected Annual Demand
Projected annual need materially exceeds historical permitting levels, especially for multi-family units—an investor-relevant signal for supply-constrained rental and infill strategies.
Framingham permitted an average of 4 multi-family units per year between 2000 and 2012 against a projected annual demand of 100 units. Single-family permitting ran 15/year against 68/year of demand. A 25x shortfall on the multi-family side. The city has since acknowledged it: household projections show roughly 4,000 additional households through 2030, net annual housing unit demand of 170 units, and annual demand from householders aged 15-35 alone of 470 units.
Meanwhile the existing stock breaks down as 54% single family, 15% two-to-four family, and 31% multi-family (5+ units). That 15% band — the 2-4 unit product investors actually want — is the scarcest and most competitive segment in the city.
How Does the ADU Permitting Process Work in Framingham, MA?
Framingham permits ADUs subject to size caps in the 900–1,200 sq ft range, with a 30+ day minimum rental term. Short-term rental arbitrage is off the table. Plan for long-term tenancy underwriting only.
Timelines from local ADU builders:
•Permitting and design: 3–6 months
•Construction: 4–8 months
Call it 9–14 months from concept to certificate of occupancy. Carry cost over that window is real. Price it into the model.
Which ADU Build Type Delivers the Better ROI in Framingham, MA?
Cost estimates for Framingham ADU projects:
Data Table
Approach
Cost Range
Annual Rent Added (est.)
Simple Yield on Cost
Internal conversion (basement/attic)
$100,000 – $180,000
~$24,000–$28,000 gross
13%–28% gross / ~8%–17% net
New detached ADU
$200,000 – $350,000+
~$28,000 gross
8%–14% gross / ~5%–9% net
The conclusion isn't subtle. Internal conversions are the deal. Detached new construction is marginal. A $140,000 basement conversion that adds a legal 2BR at $2,200/mo generates roughly $26,400 in gross rent and perhaps $17,000–$18,000 in incremental NOI after expenses. That's a 12%+ return on incremental capital and, capitalized at a 6% market cap rate, roughly $290,000 of added value against $140,000 spent. A 2x equity multiple on the improvement dollar.
A $300,000 detached ADU throwing off the same $2,200/mo doesn't clear that bar. Unless your lot configuration makes the detached unit cheap — existing garage foundation, utilities already stubbed, flat grade — skip it.
Where Does Density Already Exist in Framingham, MA?
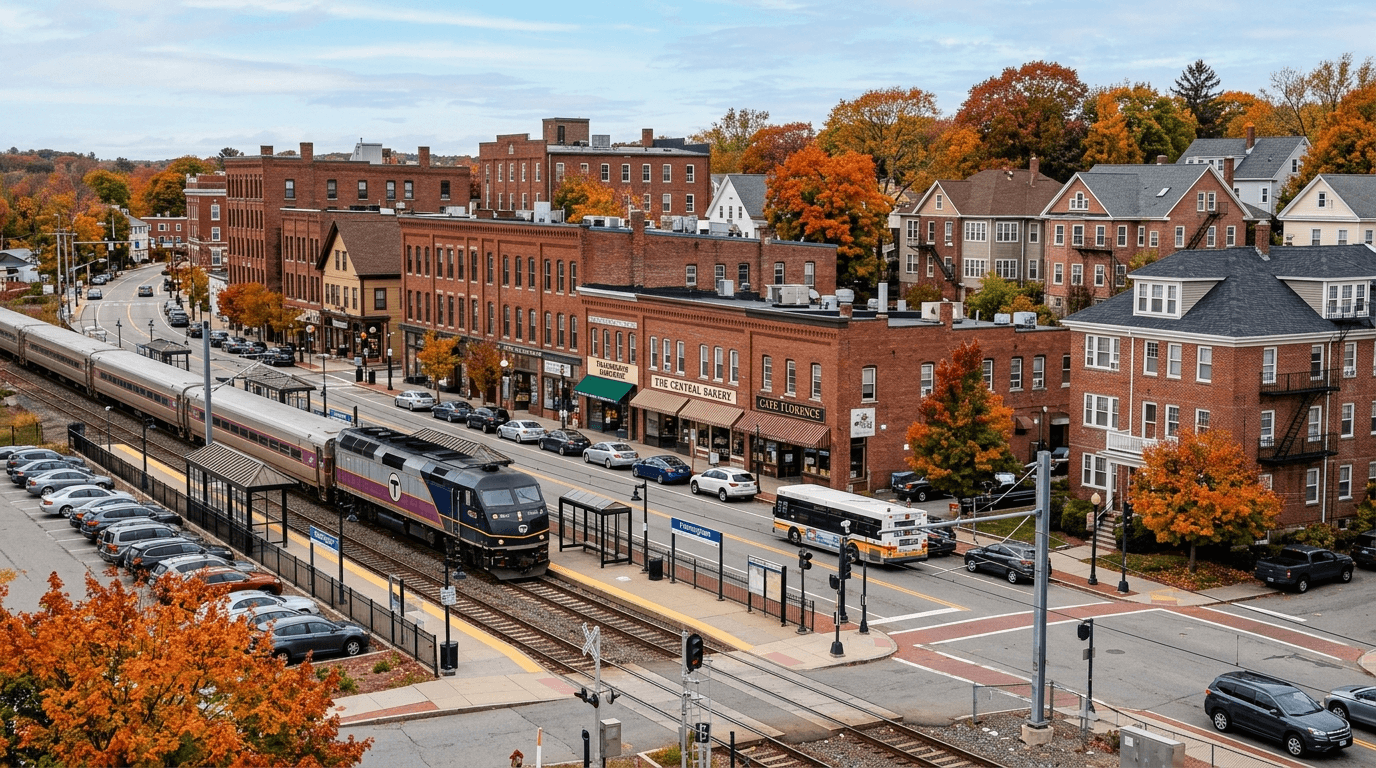
The Central Business District is already running at an estimated 25.4 dwelling units per acre against a legal requirement of 15. The downtown core is built beyond the minimum density floor. That's useful context for the MBTA Communities Act environment: 177 Massachusetts jurisdictions were required to comply by December 2025, with 115 adopting new zoning by that deadline. Transit-adjacent multi-family zoning in Massachusetts is on a one-way ratchet toward permissiveness. Land near the Framingham commuter rail station is where that optionality concentrates.
A major downtown infrastructure investment reinforces the urban-core thesis for investors watching walkable, mixed-use, and transit-adjacent revitalization plays.
CityFramingham
StateMA
Primary DepartmentPlanning & Community Development
A $40,000,000 downtown infrastructure reinvestment isn't a marketing line. It's streetscape, utilities, and drainage under a walkable district that already houses the densest residential fabric in the city. Downtown Framingham is thick with owner-operated businesses — Padaria Brasil and the surrounding Brazilian commercial corridor anchor foot traffic that supports rent-paying tenancy year-round. Infrastructure spend into a district with existing density and existing commerce is the highest-probability appreciation setup in this city.
Does the Fixer-Upper Spread Support a BRRRR Strategy in Framingham, MA?
Direct answer: Yes, but narrowly. The spread between distressed and stabilized product in Framingham is real, though the city's competitive bidding environment compresses it — you have to buy off-market or in the softer western submarket to capture it.
How Competitive Is the Buyer Environment in Framingham, MA?
This is the constraint, and it's the first thing to internalize. As of July 2026, MLSPIN shows single-family median DOM at 18 days with 3.3 months of supply. Zillow reports 61.9% of Framingham sales closing above list price and a median sale-to-list ratio of 1.014. Three numbers, one story: well-priced listings clear fast and sellers routinely capture more than asking.
You are not going to find a deeply discounted three-family sitting on MLS in Framingham for thirty days. It doesn't happen. Retail-listed distressed product gets bid up by owner-occupant house-hackers running FHA 203(k) financing, and they will outbid you — their cost of capital is lower and their yield requirement is emotional, not financial.
Where Does the Fixer-Upper Spread Actually Exist in Framingham, MA?
Two places.
1. The western submarket. The city's western edge runs softer than the north-side and Nobscot pockets: longer marketing times, less above-list bidding, and a for-sale mix skewed heavily toward Worcester Road condo product rather than single-family and small multi-family stock. Thin margins on condo flips, but a legitimate discount environment for anyone patient. Treat that softness as a negotiating posture, not a documented price series — verify current pricing listing by listing before you underwrite it.
2. The neighborhood tier spread.
Neighborhood Median ZHVI Spread
Neighborhood values vary widely, from sub-$500K pockets such as Indian Head and Wilson Street to upper-tier areas like Carlsbrooke and Concord Road West, highlighting potential acquisition tiers.
Neighborhood values vary widely, from sub-$500K pockets such as Indian Head and Wilson Street to upper-tier areas like Carlsbrooke and Concord Road West, highlighting potential acquisition tiers.
Indian Head at $481,877, Wilson Street at $488,639, and Farm Road at $519,028 sit roughly $460,000–$500,000 below Carlsbrooke at $982,022 and Concord Road West at $884,649. For a value-add operator, the sub-$500K pockets are where the basis works. Rents across a city this size don't vary by 2x the way values do, so the lower-basis neighborhoods produce structurally better gross rent multipliers. That's the entire arbitrage in one chart.
What Do Renovation Costs Run on Framingham, MA Multi-Family?
For MetroWest multi-family value-add, underwrite on a per-square-foot basis and don't trust contractor verbal estimates:
•Cosmetic refresh (paint, flooring, fixtures, appliances): $35–$55/sq ft
•Full unit gut (kitchen, bath, electrical, some plumbing): $100–$160/sq ft
•Systems (boiler replacement, electrical service upgrade, roof, sub-metering): lump-sum items, not per-foot. Budget them separately. On pre-1940 Framingham triple-deckers, budget all of them.
Add 15% contingency. Then add another 10% if the building is pre-1940 and you haven't opened a wall yet. The stock here is old, and knob-and-tube surprises are routine.
Will a Post-Rehab Refinance Return Your Capital in Framingham, MA?
The BRRRR question is whether ARV supports a cash-out refinance that returns your capital. Run it honestly:
•Acquisition on a distressed 3-family in a sub-$500K-ZHVI pocket: $550,000–$620,000
•Renovation: $150,000–$220,000 for full stabilization across three units
•All-in basis: $700,000–$840,000
•Stabilized gross rents at market: $6,600–$7,200/mo
•Stabilized NOI: $46,000–$52,000
•Value at a 6% cap: $770,000–$865,000
At 75% LTV on the high end you're pulling roughly $650,000 against an $840,000 basis. You don't get all your capital back. You get most of it, plus a stabilized asset with a low tax basis, a $11.94 tax rate, and a supply gap running 25-to-1 against new multi-family production.
That's the realistic Framingham BRRRR outcome: a partial capital return, not a full one. Anyone claiming they're infinite-returning three-deckers in a market where 61.9% of sales close above list and single-family listings go pending in under three weeks is selling something.
What's the Bottom-Line Investment Case for Framingham, MA?
Direct answer: Buy Framingham for supply scarcity, tax-rate advantage, and unit-addition optionality — not for day-one cash flow.
The scorecard as I read it in September 2026:
Supports the buy:
•Structural multi-family undersupply: 4 units/year permitted historically vs. 100/year of projected demand
•Residential tax rate 4% below the state average at $11.94/$1,000
•Value basis of $663,061 against Middlesex County's $814,047 — the county's fundamentals at the state's price
•$40M in downtown infrastructure reinvestment with existing density already at 25.4 units/acre in the CBD
•ADU internal conversions at $100K–$180K producing double-digit yields on incremental capital
•Corporate employment base (Bose, Staples, TJX, HomeGoods, Cumberland Farms) plus Framingham State and MassBay supporting a durable renter pool
Argues for discipline:
•Rents are flat to down — ZORI -2.6% year over year. No rent growth in the model.
•Multi-family listing inventory is effectively nonexistent at 9 active listings as of May 2026. Sourcing is the binding constraint.
•An 18-day single-family DOM and 61.9% of sales closing above list mean retail-listed value-add gets bid to efficiency
•50% of local renters are already cost-burdened — limited headroom to push rents
•Old stock, real capex, and 47 inches of snow a year
If you're running a spreadsheet on a Framingham three-family, two lines decide the deal: your basis relative to the neighborhood ZHVI tier, and whether there's a legal path to a fourth door. Everything else is noise. Get those two right and this market rewards you over a ten-year hold. Get them wrong and you own a negative-carry asset in a market where rents aren't currently bailing anyone out.
Want the rent roll stress-tested before you commit earnest money? Bring me the address and the seller's P&L and we'll build the real model.
Local Spots & Favorites
Framingham Market Statistics
Median sale price, days on market, and closed sales by property type.
Is Framingham, MA a good market for real estate investors?
Framingham, MA is a supply-constrained investment market where small multi-family inventory is extremely limited. As of May 2026, there were only 9 active multi-family listings and 2 closed sales, so sourcing is often the main challenge. The investment case is strongest for buyers focused on supply scarcity, tax-rate advantage, and unit-addition potential rather than day-one cash flow.
Are condos and townhomes in Framingham, MA more affordable than single-family homes?
Yes. As of July 2026, the median condo/townhouse sale price in Framingham, MA was $350,450, compared with a $755,000 median sale price for single-family homes. That price gap makes condos and townhomes a lower-cost entry point, though condo inventory showed 8.8 months of supply and a 37-day median days on market during that period.
How affordable is Framingham, MA compared with Middlesex County?
Framingham’s typical home value was $663,061, which was close to the Massachusetts benchmark of $661,896 and below the Middlesex County figure of $814,047. This means buyers are getting a Middlesex County location at a price basis closer to the statewide level. For investors, that relative discount is a major part of the market thesis.
What should investors know about rental affordability in Framingham, MA?
Framingham’s average rent was $2,354 as of August 31, 2026, above the national average of $1,948. However, rents were down 0.7% month over month and 2.6% year over year, so investors should not rely on near-term rent growth. About 50% of Framingham renters are cost-burdened, which limits how aggressively rents can be pushed.
Does Framingham, MA have good transportation access for renters and commuters?
Framingham, MA has transit-adjacent investment potential near the Framingham commuter rail station. Land near the station is where future multi-family zoning optionality is most concentrated. Downtown Framingham also benefits from existing density and a $40 million infrastructure reinvestment focused on streetscape, utilities, and drainage.
What role do schools play in Framingham, MA real estate demand?
Framingham, MA offers access to a Middlesex County location and school access at a home value level closer to the Massachusetts statewide benchmark than the county benchmark. This relative pricing position supports demand from buyers who want county fundamentals without paying the higher Middlesex County typical home value. For investors, that helps support the long-term hold thesis.
Are multi-family properties in Framingham, MA good for cash flow?
Framingham, MA is not primarily a day-one cash flow market at retail pricing. A sample three-family acquired around $750,000 and grossing about $6,600 per month would likely produce an estimated $44,000 to $47,000 in NOI, or roughly a 5.9% to 6.3% unlevered cap rate. With current financing, that is generally thin-to-neutral cash flow with 25% down and weaker with higher leverage.
Can investors add value with ADUs in Framingham, MA?
Yes, but internal conversions are the stronger opportunity. Framingham permits ADUs with size caps in the 900–1,200 square foot range and a 30-day minimum rental term, so underwriting should assume long-term tenants, not short-term rentals. Internal conversions are estimated at $100,000 to $180,000 and can produce stronger yields than detached ADUs, which are estimated at $200,000 to $350,000 or more.